South Carolina Audi Q7 Insurance

9:00am - 5:00pm Mon-Fri
Will Reply in 15min*
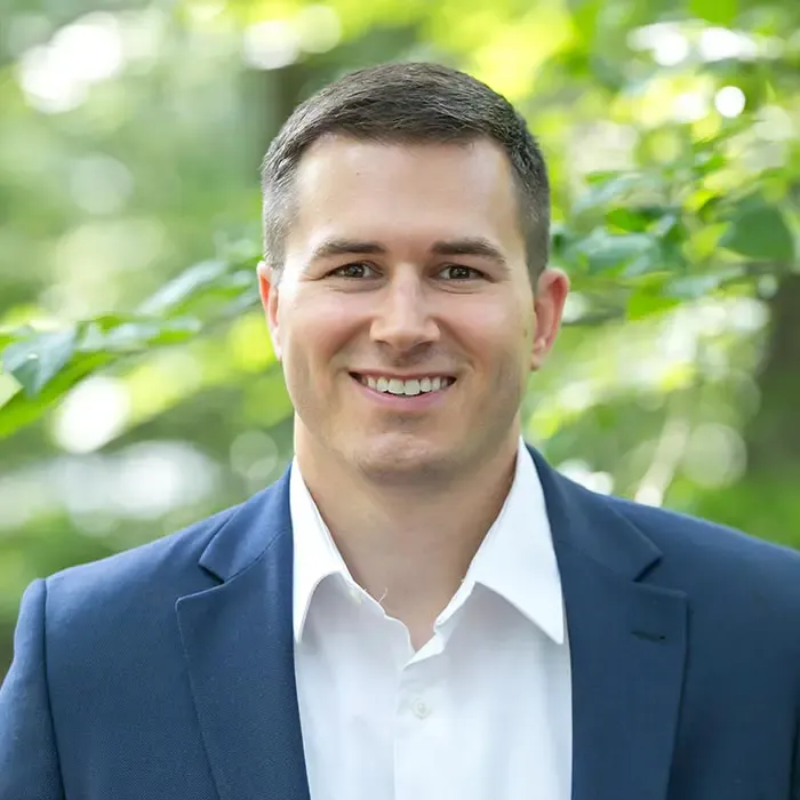
The Audi Q7 is one of the most popular family SUVs on the road, and insuring one in South Carolina comes with a unique set of considerations. Between the state's coastal storm exposure, high deer populations in the Upstate, and a mandatory uninsured motorist requirement you won't find in most other states, your policy needs to do more than check a box. This guide to Audi Q7 insurance in South Carolina covers everything from liability and gap coverage to hurricane damage and ways to keep your premiums reasonable.
Whether you're financing a brand-new Prestige trim or picked up a certified pre-owned Premium Plus, the choices you make on your policy will affect your wallet for years. South Carolina's insurance regulations shifted in 2026, too, making this a good time to review what you actually need versus what the state requires.
Factors Influencing Audi Q7 Insurance Rates in South Carolina
Several variables determine what you'll pay each month. Some are within your control, and others are baked into the vehicle itself or where you park it at night.
Luxury SUV Performance and Repair Costs
The Q7 isn't just a big SUV. It's built on a platform shared with the Porsche Cayenne and Bentley Bentayga, and that engineering shows up in your repair bills. Aluminum body panels, adaptive air suspension, and a supercharged or turbocharged powertrain all push parts and labor costs well above what you'd pay on a Toyota Highlander or Honda Pilot.
A cracked windshield on a Q7 equipped with Audi's driver-assist camera array can cost two to three times what a standard windshield replacement runs. Insurers factor these repair expenses directly into your premium. The Prestige trim, with its head-up display and Matrix LED headlights, typically costs more to insure than the base Premium model for exactly this reason.
Impact of South Carolina's Coastal Weather and Traffic Patterns
South Carolina sits in the Atlantic hurricane corridor, and comprehensive claims spike every storm season from June through November. Flood damage, wind-driven debris, and falling trees are all covered under comprehensive, but insurers price that risk into your rate based on your ZIP code.
Premiums in Greenville tend to run lower than those in Charleston or Columbia, partly because of reduced hurricane exposure and partly because of lower traffic density. If you live on the coast, expect your comprehensive premium to reflect that geography. The Lowcountry's deer population also contributes to animal-strike claims, though the Upstate sees its share as well, especially during fall mating season.
Audi Safety Features and Driver Assistance Tech
On the flip side, the Q7's safety profile works in your favor. The vehicle earns strong crash-test ratings, and Audi's standard suite of driver-assist features, including automatic emergency braking, lane-departure warning, and adaptive cruise control, can qualify you for discounts with many carriers.
The Quattro all-wheel-drive system also plays a role. Insurers recognize that AWD vehicles handle better in wet conditions, which matters in a state that averages around 49 inches of rain per year. That said, not every carrier weighs these features the same way, so it pays to ask specifically about safety-equipment discounts when you're shopping quotes.
By: David Ashton
Owner and Agent at Southern Insured
South Carolina Minimum Requirements vs. Recommended Coverage
Understanding the gap between what the state demands and what actually protects a $60,000-plus vehicle is critical.
State-Mandated Liability and Uninsured Motorist Limits
South Carolina requires liability coverage at 25/50/25, meaning $25,000 per person for bodily injury, $50,000 per accident, and $25,000 for property damage. Here's what makes the state unusual: uninsured motorist coverage must match those same 25/50/25 minimums. Most states either don't require UM coverage at all or set it at a lower threshold.
While UM coverage is mandatory, underinsured motorist (UIM) coverage remains optional. That's a gap worth closing, because a driver carrying only $25,000 in liability won't come close to covering the medical bills from a serious collision. You can elect UIM coverage to fill that shortfall.
Comparison: Basic State Minimums vs. Full Coverage for Luxury Vehicles
Carrying only the state minimum on an Audi Q7 is a significant financial risk. If you cause an accident that totals someone else's newer vehicle, $25,000 in property damage liability might not cover half the repair bill. And if your own Q7 is damaged, minimum liability does nothing to fix it.
For a vehicle in this price range, most insurance professionals recommend at least 100/300/100 liability limits, plus comprehensive and collision with a $500 or $1,000 deductible. Adding an
umbrella policy is also worth considering if you have
assets to protect beyond the vehicle itself.
Choosing the right tier depends on whether you own or finance the vehicle, how much risk you're comfortable absorbing, and whether you park near the coast.
Comparison Chart: Coverage Tiers for an Audi Q7
| Coverage Element | State Minimum | Mid-Tier | Full Protection |
|---|---|---|---|
| Bodily Injury Liability | 25/50 | 100/300 | 250/500 |
| Property Damage Liability | $25,000 | $100,000 | $100,000 |
| Uninsured Motorist | 25/50 (required) | 100/300 | 250/500 |
| Underinsured Motorist | Not required | 100/300 | 250/500 |
| Collision | None | $1,000 deductible | $500 deductible |
| Comprehensive | None | $1,000 deductible | $500 deductible |
| Gap Coverage | None | Optional | Included |
| Rental Reimbursement | None | Optional | Included |
One thing to keep in mind: if you're leasing or financing your Q7, your lender almost certainly requires full coverage with collision and comprehensive. You won't have the option of carrying only state minimums until the loan is paid off.
Gap coverage deserves special attention here. A new Q7 depreciates the moment you drive it off the lot, and if it's totaled in the first couple of years, your loan balance could exceed the vehicle's actual cash value by thousands of dollars. Gap insurance covers that difference.
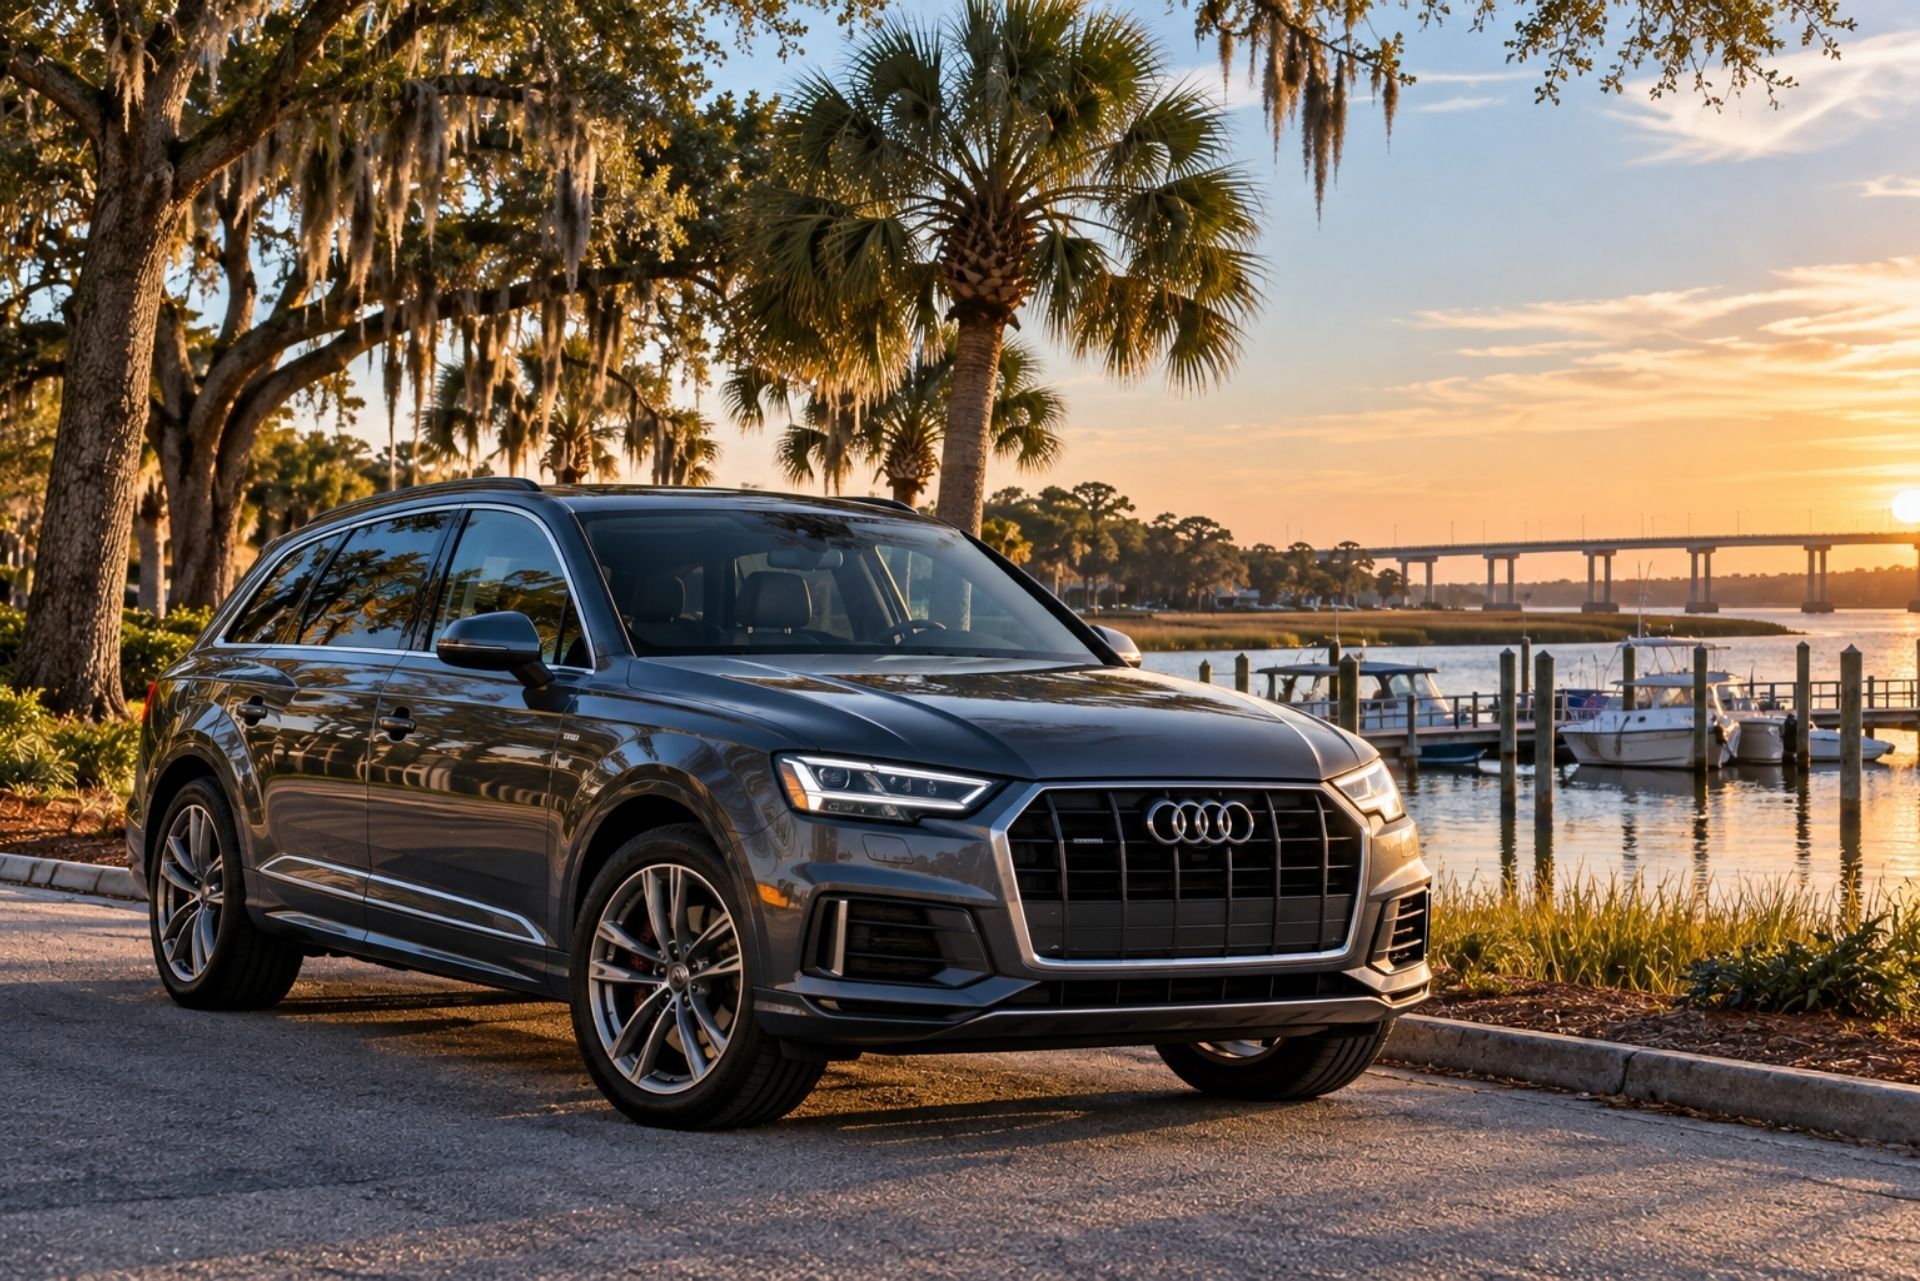
Insuring a luxury SUV doesn't have to break your budget. There are real, practical strategies to bring your rate down without sacrificing the coverage you need.
Bundling Policies and Multi-Vehicle Discounts
Most carriers offer a discount of 5% to 25% when you bundle your auto policy with homeowners or renters insurance. If your household has more than one vehicle, a multi-car discount can shave even more off the total.
Ask about loyalty discounts as well. Some insurers reward customers who've been with them for three or more years. Regional carriers operating in South Carolina sometimes offer more competitive rates on luxury vehicles than the national brands, so don't limit your search.
Safe Driver Programs and Telematics
Telematics programs, where you install a plug-in device or use a smartphone app that tracks your driving habits, can yield meaningful discounts if you drive conservatively. These programs monitor braking patterns, speed, mileage, and time of day. If you're primarily using your Q7 for school runs and weekend errands rather than long highway commutes, your data could earn you a lower rate.
A clean driving record remains the single biggest factor in your premium. One at-fault accident or speeding ticket can push your rate up by 20% or more for three to five years. Defensive driving courses approved by the state can also qualify you for a small discount, and they're typically available online.
A 2026 regulatory change worth watching: the Insurance Rate Reduction and Policyholder Protection Act may alter South Carolina's long-standing free windshield replacement mandate, potentially allowing insurers to offer policies with glass deductibles in exchange for lower overall premiums. For Q7 owners, whose windshield replacements are expensive due to embedded sensors, this trade-off requires careful thought.
Separately,
proposed tort reform under Senate Bill S. 244 could allow insurers to delay claim payments for up to 90 days without facing bad-faith penalties. If that provision passes, having an emergency fund or rental reimbursement coverage becomes even more important.
Common Questions About Insuring Your Audi
Why is insurance for a Q7 more expensive than a standard SUV? The Q7 uses aluminum body panels, advanced electronics, and specialized parts that cost significantly more to repair than those on mainstream SUVs. Insurers base premiums partly on projected claim costs, and luxury vehicles consistently generate higher repair bills.
Does my location in South Carolina change my monthly rate? Yes, and sometimes dramatically. Coastal areas like Charleston carry higher comprehensive premiums due to hurricane and flood risk, while inland cities like Greenville generally see lower rates. Even your specific neighborhood's crime statistics and traffic density factor in.
What happens if I use my Q7 for a ride-sharing service? Your personal auto policy almost certainly excludes commercial use, including ride-sharing. If you drive for Uber or Lyft, you'll need a ride-share endorsement or a commercial policy. Failing to disclose this use could void your coverage entirely if you file a claim while carrying passengers for hire.
Is Gap insurance necessary for a new Audi Q7? If you financed or leased the vehicle, gap coverage is strongly recommended. New Q7s can lose a significant portion of their value in the first two years, and without gap insurance, you'd owe the difference between your loan balance and the insurer's payout if the vehicle is totaled.
How do Audi's Quattro system and safety ratings affect my premium? Quattro AWD and the Q7's strong crash-test performance can qualify you for discounts with certain carriers. Not all insurers weight these features equally, though, so it's worth requesting itemized quotes that show exactly which discounts are being applied.
Making the Right Choice for Your Audi
Getting the right insurance for your Q7 in South Carolina means balancing the state's unique requirements with the realities of owning a luxury SUV. The mandatory uninsured motorist coverage is a good start, but it's not nearly enough on its own. You need comprehensive and collision coverage that accounts for the vehicle's repair costs, gap coverage if you're financing, and liability limits high enough to protect your personal assets.
Shop at least three to five quotes, including from regional carriers that specialize in the South Carolina market. Ask each insurer specifically about discounts for Audi's safety technology, bundling opportunities, and telematics programs. Review your policy annually, especially as 2026 legislative changes around windshield coverage and tort reform take effect.
Your Q7 is built to protect your family on the road. Make sure your insurance policy is built to protect your finances off it.
About The Author:
David Ashton
As Owner and Agent at Southern Insured, I’m passionate about helping families and businesses in South Carolina find coverage that truly fits their needs. With a background in accounting and years of experience as an independent agent, I value the freedom to recommend what’s best for each client. I enjoy spending time with my wife and children, volunteering at my church, and exploring everything the Upstate has to offer.
Personal Insurance Solutions to Protect Your Self & Family
MANAGE YOUR PERSONAL RISK
We love our clients

Sarah Gibbs
Commercial Insurance Client

Couldn't be happier! If you're looking for home insurance. look no further, The Southern Insurance Group is a great place to get insurance. They really go above and beyond helping you find the best bang for your buck. We own a rental business and a construction company, First Choice Constructors, and Rachel did a great job helping our company find exactly what we needed. Even when her phone was broken, Rachel sent texts and emails communicating clearly and efficiently. She's a true gem to The Southern Insurance Group. It's a pleasure doing business with them.
Mark H.
Personal Insurance Client
Peyton was a much needed change from my last agent who didn’t serve me very well. Peyton is a breath of fresh air. I have all my business insurances through him and loved that he made it much easier than I expected! Definitely recommend!

Cristal N.
Personal Insurance Client
Rachel was very helpful, answered all our questions, talked to the salesman we were buying the car from, and had everything ready to go for a totally new policy within an hour.
The next day we had our older car added to the policy as well, it was quick, easy and friendly. We will be doing all our future car insurance needs through Rachel.

Sabrina C.
Commercial Insurance Client
David Mosely was so helpful! He walked me through my policy and my options and truly could not have been more helpful. I don't know anyone else who would say they enjoyed their experiences trying to find insurance, but with his help I not only got insured, but learned about exactly what I am paying for.
Alex
Personal Insurance Client
Rachel at Southern Insurance Group is great. She is super helpful and nice. This is my go to place for commercial truck insurance in Greenville, SC.

Stephanie M.
Personal Insurance Client
Working with David was amazing! He explained different coverage options and what they all meant which allowed us to make informed decisions based on our needs. His knowledge around insurance is phenomenal and he’s a fun person to talk to. I highly recommend!!
Commercial Insurance Solutions to Protect Your Business
THE BEST INSURANCE COVERAGE FOR YOUR BUSINESS
Industries We Serve
WE PROTECT THESE BUSINESS IN SOUTH CAROLINA, NORTH CAROLINA, & GEORGIA
Contractors
Covers liability, property damage, and worker's compensation for contractors.
Restaurants
Protects against property damage, liability, and business interruption for restaurants.
Real Estate Investors
Safeguards investment properties from damages, liability, and income loss.
Insurance News and Insights
BLOG UPDATES
Support, answer and help, get in touch
Address office
5 Century Dr #130, Greenville, SC 29607
1901 Main Street, Floor 18
Columbia, SC 29201
Mailing Address
PO Box 202 Greenville, SC 29602
Greenville, SC
864-626-6181