South Carolina Lincoln Navigator Insurance

9:00am - 5:00pm Mon-Fri
Will Reply in 15min*
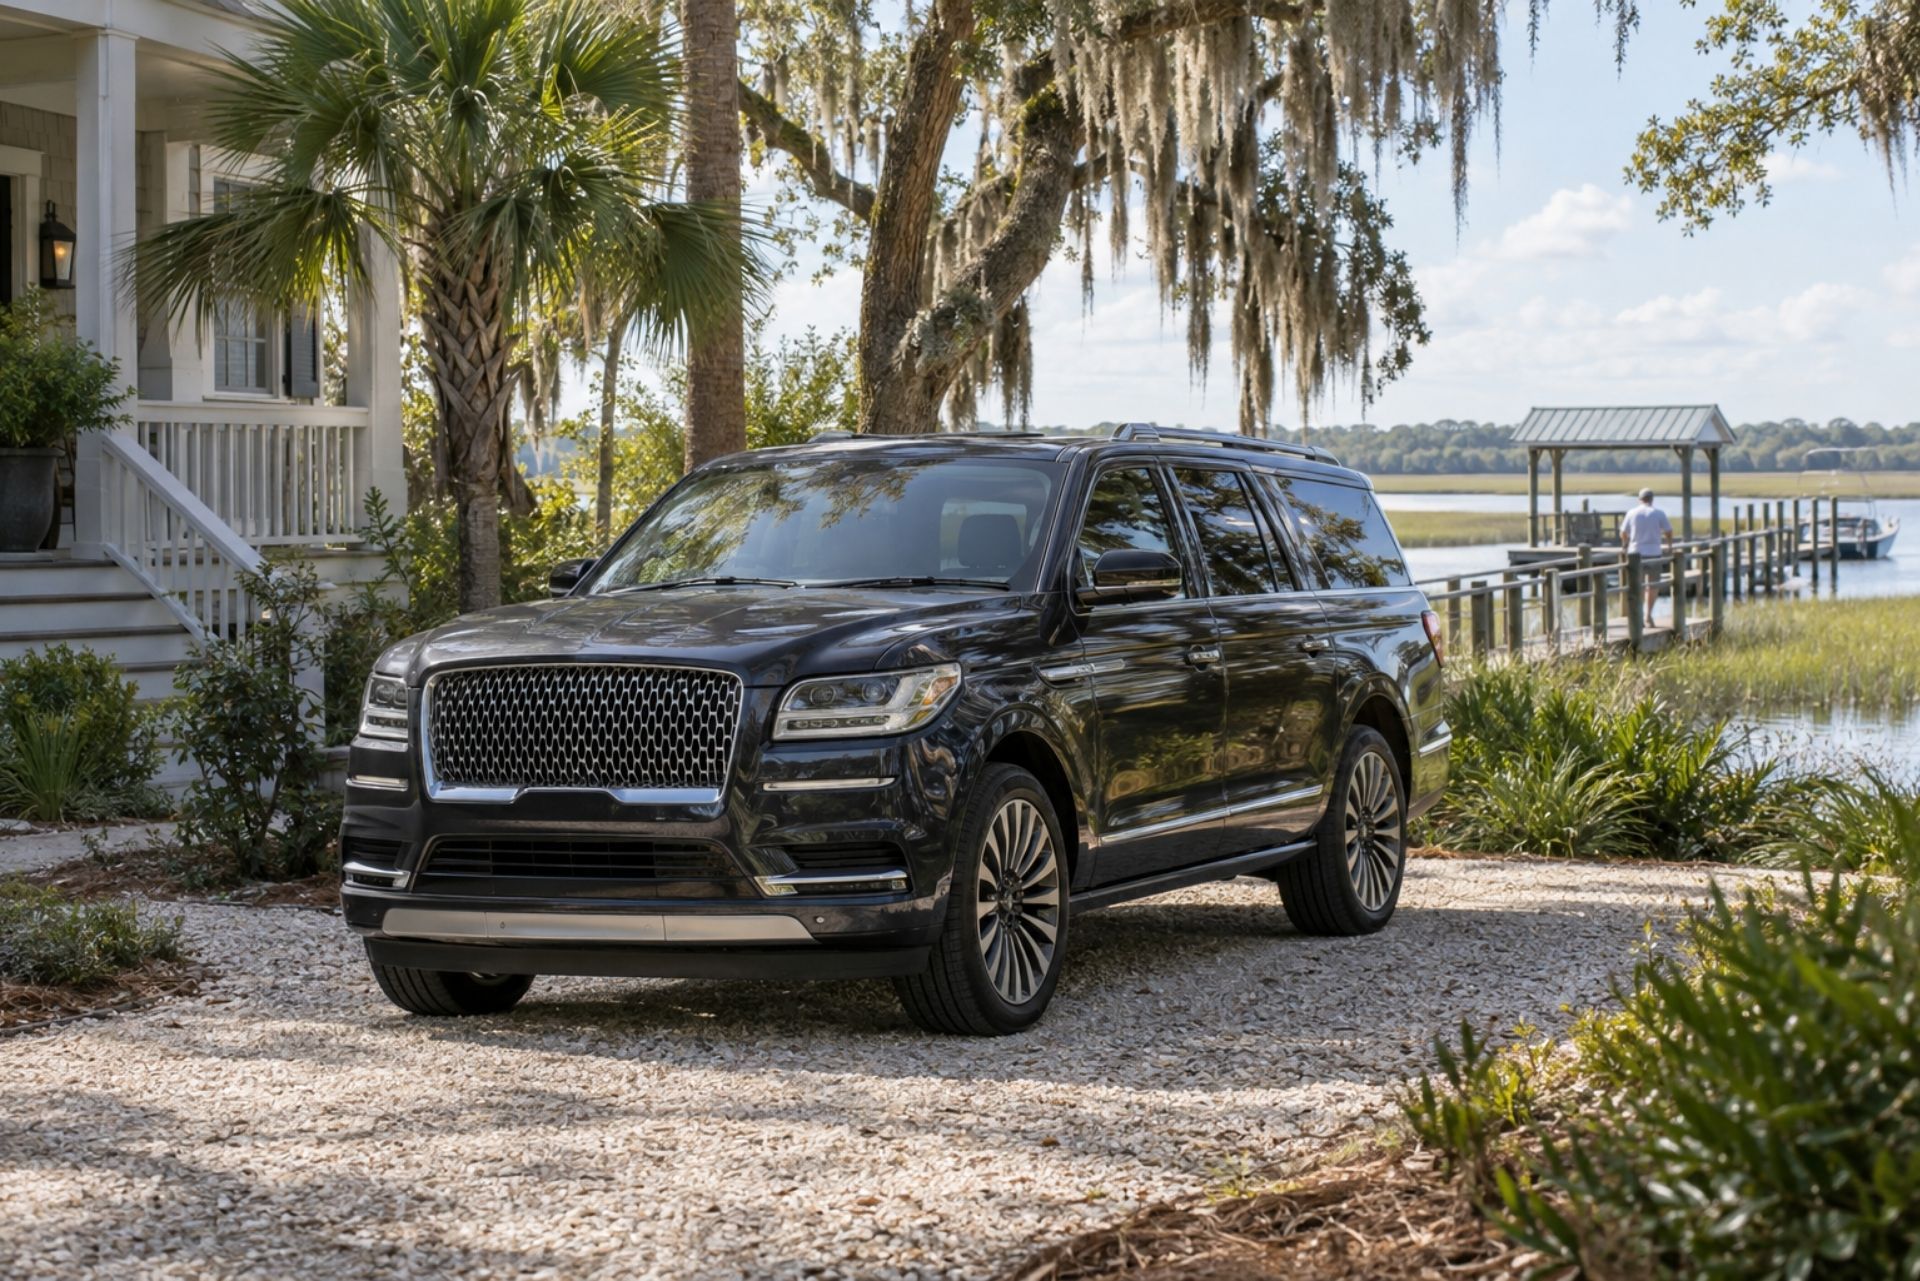
Owning a Lincoln Navigator in South Carolina means you're driving one of the most capable luxury SUVs on the road, but it also means your insurance policy needs to work harder than average. Between the state's high rate of uninsured drivers, seasonal hurricane exposure along the coast, and the sheer cost of repairing a vehicle packed with advanced sensors and cameras, getting the right coverage isn't just about checking a box. It's about protecting a significant investment from risks that are specific to this state and this class of vehicle.
This guide covers everything you need to know about
insuring your Navigator in South Carolina:
high-limit liability, uninsured motorist protection, comprehensive coverage for deer strikes and flood damage, and gap insurance for new purchases. Whether you're parking in downtown Charleston or commuting through the Upstate, the right policy structure makes all the difference.
The Navigator sits in a premium insurance tier, and for good reason. Its MSRP typically starts above $80,000 for the standard model and can exceed $110,000 for the Black Label or L (extended wheelbase) trims. Insurers don't just look at the sticker price, though. They factor in repair complexity, parts availability, theft rates, and the cost of replacing advanced driver-assistance technology.
Why Luxury SUVs Command Higher Premiums
A fender bender that might cost $1,500 to fix on a mid-size sedan can run dramatically higher on a Navigator. Modern vehicles with sensors, cameras, and advanced safety systems often cost $3,000 to $5,000 or more per repair, and the Navigator is loaded with them. Its aluminum-intensive body panels require specialized equipment and trained technicians, which limits the number of shops that can handle the work.
The Navigator also competes with vehicles like the Cadillac Escalade and BMW X7. Compared to its non-luxury platform cousin, the Ford Expedition, the Navigator's repair costs are noticeably higher due to premium materials and proprietary Lincoln components. That gap in repair expense translates directly into higher premiums.
South Carolina Specific Rating Factors
Your ZIP code matters more than you might think. Drivers in coastal regions like Charleston and Myrtle Beach face what's sometimes called a "hurricane tax," with comprehensive coverage premiums for flood and wind damage running significantly higher than what drivers pay in Columbia or Greenville. Insurers also weigh local crime rates, traffic density, and even the prevalence of deer-vehicle collisions, which are common in rural parts of the state from October through December.
South Carolina's overall claims environment plays a role too. With roughly
12.3% of drivers in the state carrying no insurance at all, the risk of an accident with an uninsured motorist is real, and that risk gets priced into your policy.
By: David Ashton
Owner and Agent at Southern Insured
South Carolina Minimum Requirements vs. Recommended Coverage
South Carolina requires liability coverage, but the state minimums are designed as a legal floor, not as adequate protection for a luxury SUV owner. Under S.C. Code § 38-77-140, the mandatory limits are 25/50/25: $25,000 per person for bodily injury, $50,000 per accident, and $25,000 for property damage (https://insurancerateguard.com/insurance-101/south-carolina-car-insurance/). For someone driving an $80,000-plus vehicle, those numbers leave enormous gaps.
Comparison of Coverage Levels for High-Value SUVs
Here's where the math gets uncomfortable. If you cause an accident that totals someone else's newer vehicle, $25,000 in property damage coverage might not even cover half the bill. And if you're hit by one of those uninsured drivers, minimum coverage leaves you exposed.
For Navigator owners, most independent agents recommend liability limits of at least 100/300/100, with a $1 million umbrella policy for those with significant assets. One thing to keep in mind: South Carolina law requires that uninsured motorist coverage be included in every auto policy at limits matching your liability levels. You can reject UM coverage in writing, but doing so with a 12.3% uninsured driver rate is a gamble most financial advisors would discourage.
Comprehensive and collision coverage aren't legally required, but any lender financing your Navigator will mandate both. Even if you own the vehicle outright, skipping comprehensive on a vehicle this valuable leaves you unprotected against theft, hail, flooding, and animal strikes.
| Coverage Type | Basic (State Minimum) | Premium (Recommended for Navigator) |
|---|---|---|
| Bodily Injury Liability | 25/50 | 100/300 or higher |
| Property Damage Liability | $25,000 | $100,000 |
| Uninsured Motorist (BI) | 25/50 (can reject in writing) | 100/300 (matching liability) |
| Uninsured Motorist (PD) | $25,000 (can reject in writing) | $100,000 |
| Comprehensive | Not required | $500 deductible recommended |
| Collision | Not required | $500-$1,000 deductible |
| Gap Insurance | Not included | Recommended for financed/leased |
| Umbrella Policy | Not included | $1M recommended |
| Rental Reimbursement | Not included | $50-$75/day for 30 days |
The difference in annual premium between basic and premium coverage can be substantial, but the protection gap is even larger. A single at-fault accident or a flood event could cost you tens of thousands out of pocket with minimum coverage.
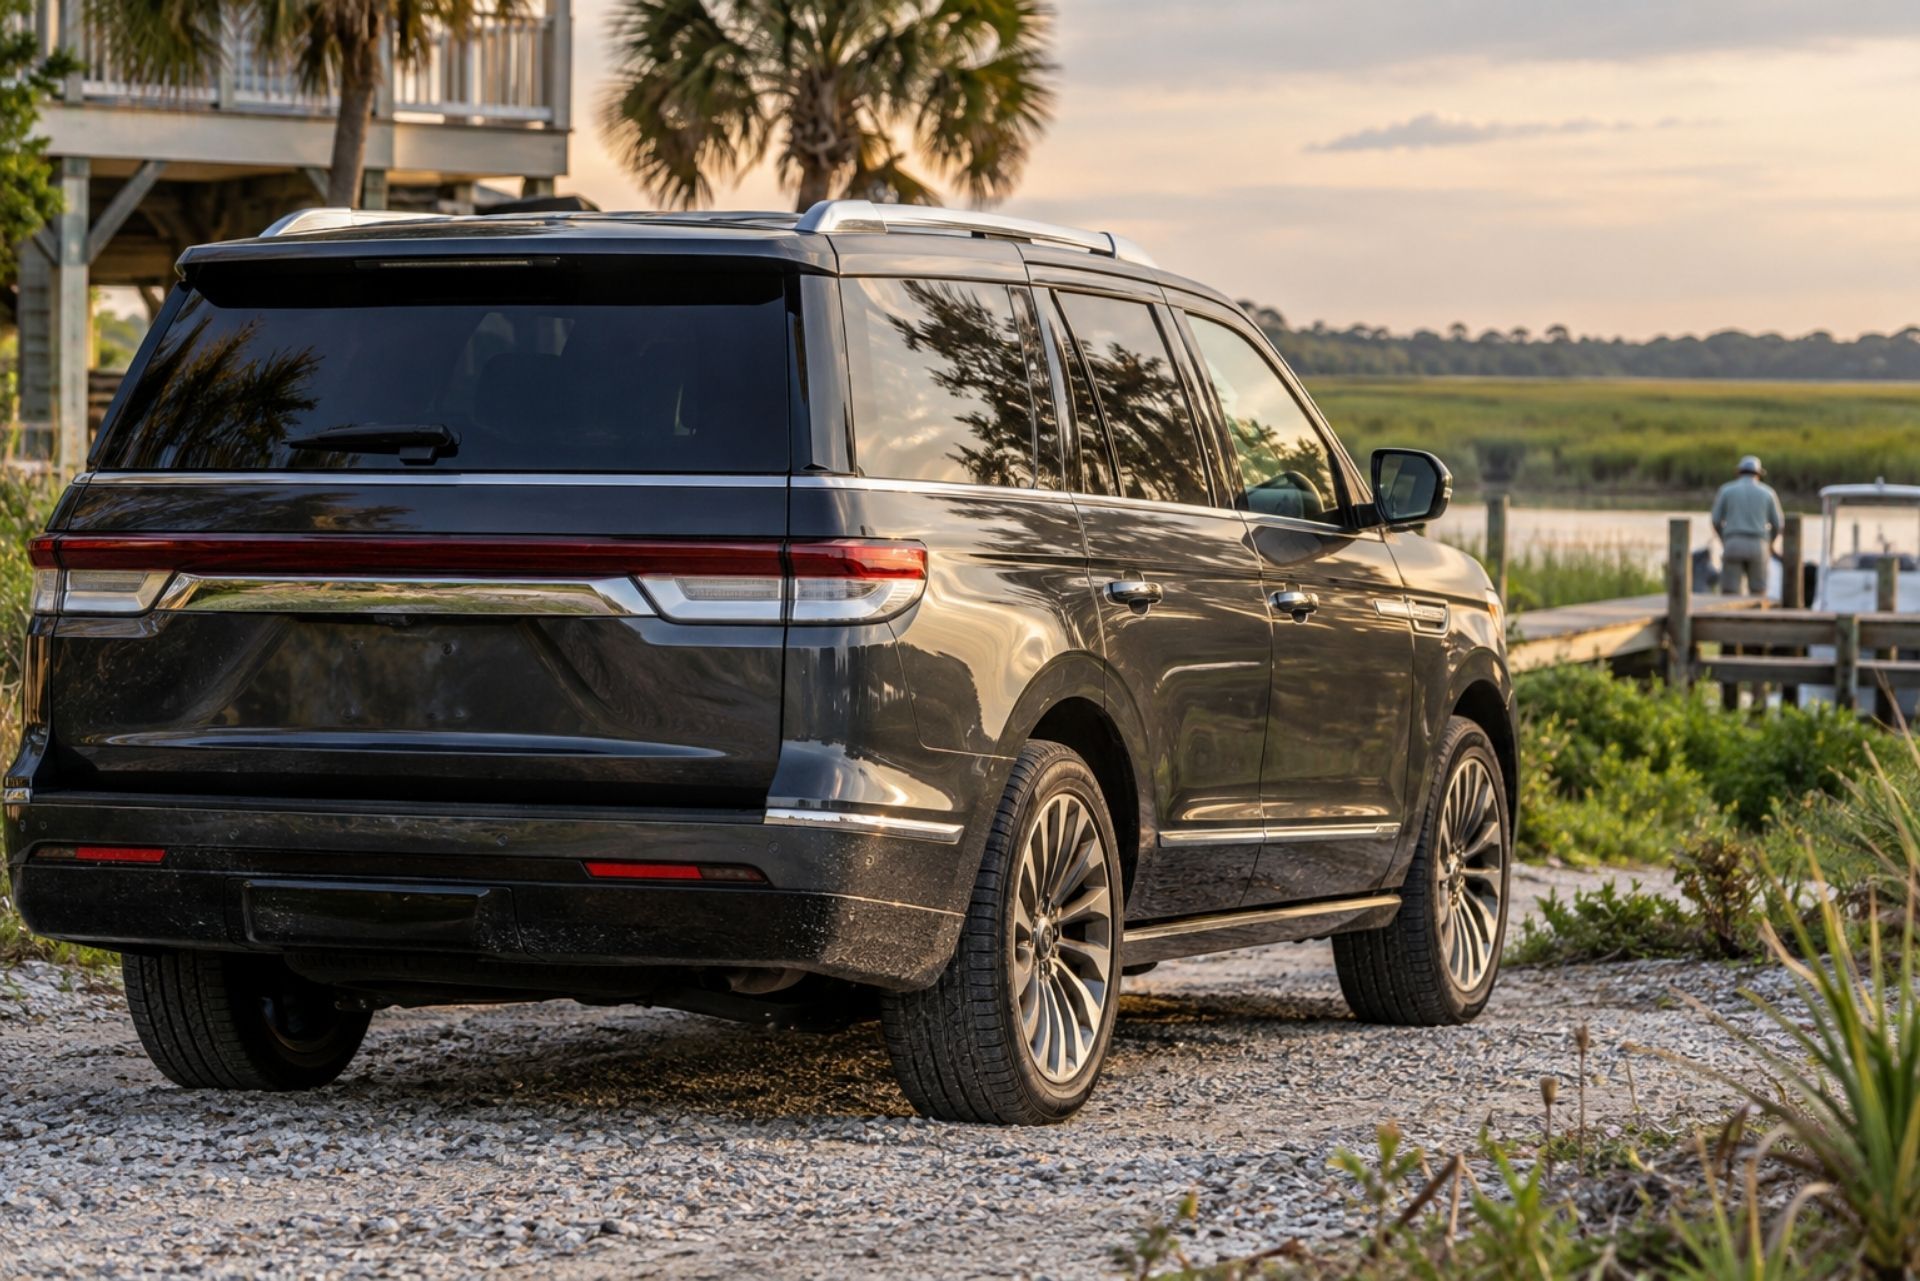
Insurance for a Lincoln Navigator in South Carolina doesn't have to break the bank. Several strategies can bring your premium down without sacrificing the coverage you actually need.
Safety Features and Anti-Theft Discounts
The Navigator comes standard with a suite of features that many insurers reward. Lincoln's CoPilot360 system includes automatic emergency braking, blind-spot detection, lane-keeping assist, and adaptive cruise control. Ask your insurer specifically about discounts for each of these. Some carriers also offer reduced rates for vehicles equipped with factory anti-theft systems, and the Navigator's standard alarm and encrypted key fob qualify.
If you garage your Navigator overnight, mention that too. A locked garage reduces theft and weather exposure risk, and most carriers offer a small discount for it.
Bundling and Multi-Policy Savings
Combining your auto policy with homeowners or renters insurance through the same carrier typically yields a discount of 10-20%. If you have multiple vehicles in the household, insuring them all under one policy can reduce per-vehicle costs. Some regional carriers in South Carolina, like auto-home specialists operating in the Southeastern market, may offer more competitive rates on luxury SUVs than national brands.
That said, don't assume the cheapest quote is the best value. Pay attention to claims handling reputation and whether the insurer allows you to choose your own repair shop. For a vehicle like the Navigator, being forced into a non-certified body shop can mean subpar repairs on those aluminum panels and recalibrated sensors.
Is insurance for a Lincoln Navigator more expensive than other SUVs?
Yes, generally. The Navigator's high MSRP, aluminum body construction, and dense array of safety technology all push repair costs above average. Expect premiums to run higher than a Ford Expedition or Chevy Tahoe, and roughly comparable to a Cadillac Escalade or BMW X7.
Does my location in South Carolina affect my rate?
It does, significantly. Coastal areas carry higher comprehensive premiums due to hurricane and flood risk. Urban areas like Columbia and Greenville may have higher collision and theft rates. Rural areas can see more deer-related claims. Your specific ZIP code is one of the strongest rating factors in your premium calculation.
What is the best way to get a cheap quote for a luxury vehicle?
Start by getting quotes from at least four or five carriers, including both national and regional companies. Make sure you're comparing identical coverage levels. Raise your deductibles to $1,000 if you can absorb that cost in a claim. Bundle policies, ask about every available discount, and maintain a clean driving record. Avoid the temptation to cut coverage limits just to lower the premium, though. On a vehicle worth this much, the savings aren't worth the exposure.
Do I need gap insurance for a new Lincoln Navigator?
If you financed or leased your Navigator, gap coverage is strongly recommended. Luxury SUVs can depreciate 20-30% in the first two years. If your Navigator is totaled in a flood or major accident during that period, your standard policy pays the current market value, not what you owe. Gap insurance covers the difference. Some Lincoln dealerships offer gap coverage at purchase, but you can often find it cheaper through your auto insurer. Check both options before signing.
Making the Right Choice for Your Luxury SUV
Insuring a Lincoln Navigator in South Carolina requires more thought than a standard vehicle policy. The combination of high repair costs, the state's uninsured motorist problem, coastal flood exposure, and active deer populations creates a risk profile that demands comprehensive, high-limit coverage.
Here's what that means for you in practical terms: don't settle for state minimums, don't skip uninsured motorist protection, and don't overlook comprehensive coverage even if you own the vehicle free and clear. If you're financing, gap insurance is close to essential for the first few years of ownership. South Carolina's requirement that UM coverage match your liability limits is actually a built-in safety net, so take advantage of it rather than opting out.
Get multiple quotes, ask about every discount your Navigator's safety features qualify for, and work with an agent who understands luxury vehicle coverage. A few hours of comparison shopping now can save you thousands in premiums and protect you from a financial hit that no one wants to face after an accident, a storm, or an encounter with a white-tailed deer on a dark Lowcountry road.
About The Author:
David Ashton
As Owner and Agent at Southern Insured, I’m passionate about helping families and businesses in South Carolina find coverage that truly fits their needs. With a background in accounting and years of experience as an independent agent, I value the freedom to recommend what’s best for each client. I enjoy spending time with my wife and children, volunteering at my church, and exploring everything the Upstate has to offer.
Personal Insurance Solutions to Protect Your Self & Family
MANAGE YOUR PERSONAL RISK
We love our clients

Sarah Gibbs
Commercial Insurance Client

Couldn't be happier! If you're looking for home insurance. look no further, The Southern Insurance Group is a great place to get insurance. They really go above and beyond helping you find the best bang for your buck. We own a rental business and a construction company, First Choice Constructors, and Rachel did a great job helping our company find exactly what we needed. Even when her phone was broken, Rachel sent texts and emails communicating clearly and efficiently. She's a true gem to The Southern Insurance Group. It's a pleasure doing business with them.
Mark H.
Personal Insurance Client
Peyton was a much needed change from my last agent who didn’t serve me very well. Peyton is a breath of fresh air. I have all my business insurances through him and loved that he made it much easier than I expected! Definitely recommend!

Cristal N.
Personal Insurance Client
Rachel was very helpful, answered all our questions, talked to the salesman we were buying the car from, and had everything ready to go for a totally new policy within an hour.
The next day we had our older car added to the policy as well, it was quick, easy and friendly. We will be doing all our future car insurance needs through Rachel.

Sabrina C.
Commercial Insurance Client
David Mosely was so helpful! He walked me through my policy and my options and truly could not have been more helpful. I don't know anyone else who would say they enjoyed their experiences trying to find insurance, but with his help I not only got insured, but learned about exactly what I am paying for.
Alex
Personal Insurance Client
Rachel at Southern Insurance Group is great. She is super helpful and nice. This is my go to place for commercial truck insurance in Greenville, SC.

Stephanie M.
Personal Insurance Client
Working with David was amazing! He explained different coverage options and what they all meant which allowed us to make informed decisions based on our needs. His knowledge around insurance is phenomenal and he’s a fun person to talk to. I highly recommend!!
Commercial Insurance Solutions to Protect Your Business
THE BEST INSURANCE COVERAGE FOR YOUR BUSINESS
Industries We Serve
WE PROTECT THESE BUSINESS IN SOUTH CAROLINA, NORTH CAROLINA, & GEORGIA
Contractors
Covers liability, property damage, and worker's compensation for contractors.
Restaurants
Protects against property damage, liability, and business interruption for restaurants.
Real Estate Investors
Safeguards investment properties from damages, liability, and income loss.
Insurance News and Insights
BLOG UPDATES
Support, answer and help, get in touch
Address office
5 Century Dr #130, Greenville, SC 29607
1901 Main Street, Floor 18
Columbia, SC 29201
Mailing Address
PO Box 202 Greenville, SC 29602
Greenville, SC
864-626-6181