SC Roofing Insurance for Open-Roof Water Damage
See How We're Different
or call us: 864-626-6181
A sudden afternoon thunderstorm rolls through Charleston while your crew has a roof stripped down to the decking. Within 20 minutes, rain pours into the homeowner's living room, soaking hardwood floors, drywall, and a ceiling fan fixture. The homeowner files a claim, and now you're staring at a five-figure liability. This scenario plays out across South Carolina every year, and it's one of the most misunderstood areas of contractor coverage. If you're a roofing contractor working in this state, understanding your insurance obligations around open-roof water damage, storm exposure, tarping, interior damage, and policy exclusions isn't optional. It's the difference between staying in business and shutting your doors. South Carolina's coastal weather patterns, combined with an evolving regulatory environment, make this a topic that deserves your full attention. The 2026 hurricane season forecast calls for 8 to 14 named storms and 3 to 6 hurricanes, which means even a below-normal season carries real risk for crews working on exposed roofs. Your general liability policy may not protect you the way you think it does. Let's break down what you actually need.
Understanding Open-Roof Exposure in South Carolina
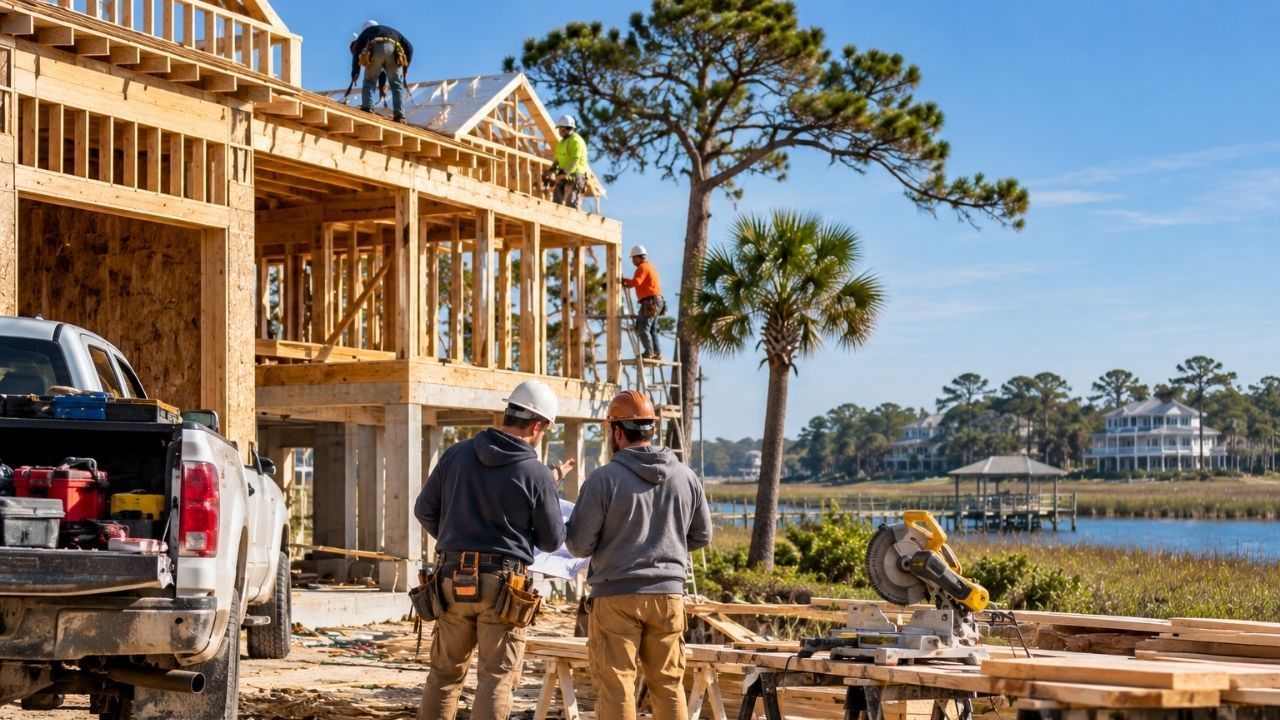
Open-roof exposure refers to any period during a roofing project when the structure lacks its protective covering. This could last anywhere from a few hours during a tear-off to several days on a larger commercial job. The problem is straightforward: an exposed roof is an invitation for water intrusion, and South Carolina's climate is happy to accept that invitation.
Coastal and Lowcountry regions see pop-up thunderstorms with little warning, especially between May and November. Inland areas like Greenville and Columbia aren't immune either, with heavy afternoon storms common throughout summer. The financial exposure for contractors during these windows can be significant.
The Risk of Sudden Coastal Storms
South Carolina's geography creates a unique weather profile. Warm, moist air from the Atlantic fuels rapid storm development, and contractors working near the coast often face conditions that shift within minutes. A clear morning forecast doesn't guarantee a dry afternoon.
The catch is that most weather apps give you a probability of rain, not a guarantee of dry conditions. Experienced crews watch radar closely, but even the best planning can't prevent every exposure event. When storms hit during an active tear-off, the damage happens fast and the liability questions start immediately.
Common Causes of Interior Water Damage Claims
Most open-roof water damage claims stem from a handful of recurring situations. Incomplete tear-offs left overnight are the most common. Crews strip shingles late in the day, run out of daylight, and a storm moves through before morning. Improperly secured tarps that blow off during wind events rank second.
Failed or missing ice-and-water shield installations also contribute. Some contractors skip underlayment steps to save time, creating vulnerability even when the roof appears covered. Each of these scenarios creates a direct path for water to reach the home's interior, damaging ceilings, walls, flooring, and personal property.
General Liability vs. Open-Roof Endorsements
Standard general liability policies are built to cover bodily injury and property damage caused by your operations. That sounds like it should include water damage from an open roof, but the reality is more complicated. Most GL policies contain exclusions that specifically limit or eliminate coverage for damage to property in your care, custody, or control.
Why Standard Policies Often Exclude Rain Damage
Your standard GL policy typically excludes damage to the specific property you're working on. This is the "your work" exclusion, and it's a big deal for roofers. If rain enters through a roof you've opened, the homeowner's interior damage may fall into a gray area. Some insurers argue this is a foreseeable risk of your operations, not an accident.
Policies also commonly exclude damage from weather events when the contractor had a reasonable opportunity to protect the structure. If you left a roof exposed overnight without adequate tarping, your insurer has grounds to deny the claim. That said, endorsements designed for roofing contractors can fill these gaps, but you need to ask for them specifically.
Coverage Comparison: Standard GL vs. Specialized Roofing Policy
| Coverage Feature | Standard GL Policy | Specialized Roofing Policy |
|---|---|---|
| Bodily injury on job site | Covered | Covered |
| Interior water damage from open roof | Typically excluded | Covered with endorsement |
| Tarping failure during storms | Often excluded | May be covered |
| Damage to homeowner's personal property | Limited or excluded | Covered up to policy limits |
| Hurricane/tropical storm exposure | Excluded in most policies | Available with wind/hail rider |
| Completed operations water intrusion | Varies | Typically included |
Comparison of Coverage Limits and Exclusions
Coverage limits for roofing contractor policies in South Carolina vary widely based on your annual revenue, crew size, and the types of projects you take on. While solo operators may pay between $430 and $780 per year for general liability, staffed businesses often utilize bundled packages including workers' compensation and tools coverage to manage their specific risks (https://www.thecontractormatrix.com/contractor-insurance-costs/south-carolina, https://www.moneygeek.com/insurance/business/contractor/roofing/cost/).
Exclusions are where the real differences show up. Wind-driven rain exclusions are common in coastal counties. Some policies exclude all weather-related damage during active construction, while others only exclude named storms. You need to read your exclusions schedule line by line, not just skim the declarations page. One thing to keep in mind: the cheapest policy almost always has the most exclusions.
Hurricane Season and Emergency Tarping Protocols
South Carolina's hurricane season runs from June through November, and even a below-normal year brings risk. Emergency tarping is both a liability protection measure and a potential revenue stream for roofing contractors. The costs and standards matter for your insurance coverage.
Emergency roof tarping in South Carolina typically ranges from $150 to $3,300, with proper securement requiring specific standards like 2x4 wooden battens. If you're tarping as part of your own project's weather protection, your insurer expects you to meet these standards. A tarp held down by cinder blocks won't satisfy most policy requirements for "reasonable precautions."
Document every tarp installation with timestamped photos. Record the materials used, the crew members involved, and the weather conditions at the time. This documentation becomes your primary defense if a claim arises.
Navigating South Carolina Insurance Requirements
South Carolina has specific requirements for roofing contractors that directly affect your insurance needs. The state's regulatory framework has shifted in recent years, and 2026 brought notable changes.
State Licensing and Proof of Financial Responsibility
South Carolina requires roofing contractors to hold a valid license through the South Carolina Contractors' Licensing Board. Part of that licensing process involves demonstrating financial responsibility, which for commercial license applicants requires a financial statement or a surety bond to determine their project bidding group limit (https://www.simplywise.com/blog/south-carolina-contractor-license/).
A significant change took effect on July 1, 2026: Senate Bill 808 expanded the list of professionals authorized to conduct insurance-related roof inspections to include home inspectors and general contractors. This changes the claims process dynamics for roofing contractors, as more parties can now formally assess roof damage for insurance purposes.
Meeting Commercial Contract Requirements
Commercial projects and HOA contracts often require higher coverage limits than residential work. You'll frequently see requirements for $2 million aggregate limits, additional insured endorsements, and waiver of subrogation clauses. If your policy doesn't include open-roof water damage coverage, you may not qualify for these contracts at all.
Property managers and general contractors are increasingly requiring roofing-specific endorsements before allowing subs on site. This trend accelerated after several high-profile water damage claims in the Myrtle Beach and Hilton Head markets.
Common Questions About Roofing Water Damage
Does my general liability policy cover interior water damage if it rains during a tear-off? Usually not without a specific endorsement. Most standard GL policies exclude damage to property in your care, custody, or control. Ask your agent about an open-roof or weather-related damage endorsement.
What happens if a homeowner's insurance claim gets denied after I've signed a contract? Under South Carolina law, homeowners have a 5-business-day window to cancel a roofing contract if their insurance claim is denied. You should build this right into your contract language.
Are tarping costs covered by my insurance? It depends on the circumstances. If you're tarping to prevent further damage during your own project, the cost may fall under your policy's mitigation obligations. If you're providing emergency tarping as a service, you'll need appropriate coverage for that work.
How is the shift to Actual Cash Value coverage affecting roofing contractors? A new federal rule allows Fannie Mae and Freddie Mac to accept Actual Cash Value coverage for roofs, which can increase homeowner out-of-pocket costs. This means more homeowners may face gaps between their insurance payout and the actual repair cost, and the liability of insurance is shifting to the homeowner in many cases.
Do I need separate coverage for hurricane season work? Many standard policies exclude named storm damage. If you work during hurricane season, which is most of the year in South Carolina, you likely need a wind and hail endorsement or a separate policy rider.
How Policy Exclusions Can Sink Your Business
Exclusions are the silent killers in roofing contractor insurance. A single uncovered water damage claim can easily reach $30,000 to $80,000 when you factor in drywall replacement, hardwood floor repair, mold remediation, and personal property damage. If your policy excludes the specific scenario that caused the damage, that bill lands squarely on your business.
The most dangerous exclusions for South Carolina roofers include weather-related damage during active construction, named storm exclusions, and the care, custody, and control limitation. Review your policy with an agent who understands roofing operations, not a generalist who sells auto insurance on the side.
The Changing Insurance Market for SC Roofers
The South Carolina roofing insurance market is tightening. Many carriers are reducing coverage on older roofs, with some moving to fire-and-lightning-only coverage. This pressure flows downhill to contractors, as homeowners with limited coverage have less money available for quality repairs.
Some contractors are responding by providing cash bids and letting homeowners handle the insurance gap themselves. This approach reduces the contractor's exposure to underpaid claims but requires clear communication and solid contract language. Your own contractor insurance needs to account for these shifting dynamics.
Steps to Take Before Hurricane Season Hits
Preparation before hurricane season isn't just smart business practice. It directly affects your insurability and your claim outcomes. Start by reviewing your policy 60 days before June 1. Confirm your coverage limits, check your exclusions, and verify that your certificates of insurance are current.
Build a weather response plan that your crew knows by heart. Identify the tarping materials you'll keep on every job site, set trigger points for stopping work based on radar, and establish a communication chain for emergency situations. Insurers look favorably on contractors who can demonstrate proactive risk management.
Protecting Your Business Before You Buy a Policy
The best insurance policy in the world won't help if your operations create unnecessary risk. Smart contractors reduce their exposure through operational practices, not just premium payments.
Reviewing the 'Care, Custody, and Control' Clause
This clause appears in nearly every GL policy and limits coverage for property that's in your possession or under your control during work. For roofers, the homeowner's interior becomes "property in your care" the moment you strip the roof. If rain damages that interior, the CCC exclusion can void your coverage.
Ask your agent to walk through this clause with you. Some policies offer a carve-out for roofing operations, while others require a separate inland marine or installation floater policy. Don't assume you're covered.
Best Practices for Mitigating Water Damage Claims
Keep tarps, battens, and fasteners on every job site, not in the warehouse. Train your crew on proper tarp installation techniques, including the 2x4 batten securement method. Never leave a roof exposed overnight without protection, even if the forecast looks clear.
Photograph the roof at the end of every workday, showing the condition of any temporary weatherproofing. Require your crew lead to sign off on weather protection before leaving the site. These habits cost almost nothing but can save your business tens of thousands of dollars in denied claims.
Your roofing contractor insurance for open-roof water damage in South Carolina needs to match the actual risks you face, not just check a box for licensing. Review your policy today, talk to an agent who specializes in contractor coverage, and make sure your operations back up your coverage. The next storm isn't going to wait for you to figure this out.
Recent posts